
Nov 12, 2026
Retiring abroad? Key questions to help you plan with confidence
For generations, the American economic bargain has been simple: Work hard, earn more over time and gradually build a better life. Owning a home became the physical embodiment of that progress, representing independence and a step toward generational wealth.
But today, many Americans are struggling to make headway. Google searches for “affordability” surged this year to their highest levels ever,1 and voters said the cost of living was the most important issue in polls going into the midterm elections.2 While politicians on both sides of the aisle campaigned on lowering prices, angst about the economy contributed to the incumbent Republican Party’s loss of both houses of Congress in the recent midterm elections.
Voters are not reacting to a temporary spike in inflation or a dip in real wages—they know the trajectory of the economy has changed. When real wages are plotted as a rolling five-year average, they are now 9.2% below where they would be had the pre-pandemic trend continued. Affordability has taken a real hit, and Americans can feel the difference.
This weaker trajectory shows no sign of reverting. The latest data from October showed that all of the gains in real wages since President Trump’s second inauguration have been undone. This means that the average American’s buying power has been flat for nearly two years.
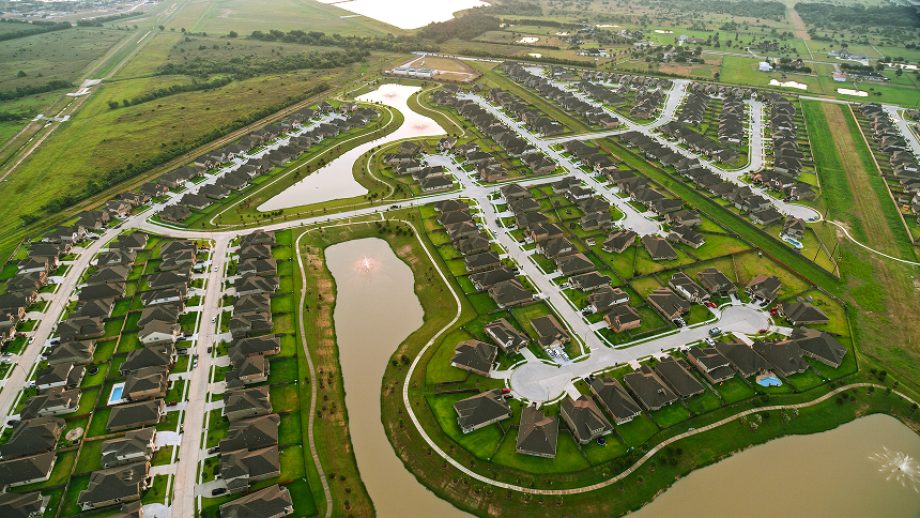
Just as housing long represented the American Dream, it now exemplifies decreasing affordability. Nationally, home sales prices are near record highs relative to incomes. While there was a similar spike during the housing bubble prior to the global financial crisis (GFC), that bubble coincided with a surge in homebuilding, allowing prices to correct severely once demand evaporated. Today, rising prices have accompanied nearly two decades of underbuilding and a shortage of homes. This means a similar price collapse is unlikely, and restoring former levels of affordability will be a challenge.
While the housing challenge is national, it is important to note it’s not uniform. It is particularly severe in expensive, supply-constrained coastal markets, where the relationship between home prices and household incomes has become increasingly stretched.
In cities like Boston, New York, San Francisco and Los Angeles, the median sale price of a home is more than six times the median family income, and that ratio climbs to almost 10 times in some markets. In major markets with less density and fewer constraints, such as Dallas, Cleveland and Pittsburgh, the ratio actually falls to around three times median family income, below the national average.3
The divide between households is also widening, regardless of region. Homeowners who bought before 2023 and secured low fixed-rate mortgage rates have largely been insulated from the increase in financing costs. At the same time, prospective buyers are facing elevated prices, higher mortgage rates, larger required down payments and rising expenses for insurance, taxes and maintenance.
Younger Americans are feeling the effects most acutely. Nationally, 65% of families owned their home as of the second quarter of 2026, but only 35% of Americans under 35 did, and the trend for the younger cohort is downward as rising costs force them to save up for longer before buying. The median age of first-time homebuyers hit 40 years in 2025, a record high and up from 33 in 2021.4
The housing affordability issue is inextricably tied to the broader economic landscape. Mortgage rates, which dipped below 6% early in the year, quickly reversed course and have risen steadily since the Iran conflict began, as inflation fears drove yields up across the board. They now stand above 7%, near multi-decade highs. To put this in perspective, an equilibrium mortgage rate implied by J.P. Morgan Asset Management’s Long-Term Capital Market Assumptions is far lower, near 5.8%.5
Higher mortgage rates increase monthly payments for new buyers and reduce purchasing power. They also discourage existing homeowners from moving: As we’ve noted, many owners have locked in much lower rates and would need to surrender them to purchase a new home.6 This “lock-in effect” limits the number of existing homes reaching the market, further constraining inventory. Illustrating the problem, pending home sales fell to their lowest level ever in September.7
Mortgage spreads, or the gap between Treasury yields and the mortgage rates being offered, have also widened as interest rate volatility soared. Additionally, the difference in mortgage loan providers has pushed spreads wider. In 2008, around 60% of mortgages originated with banks. However, many banks left the mortgage market after new regulations and capital requirements were imposed in the wake of the GFC. In today’s market, nonbanks predominate, and only 35% of mortgages originate with banks.8
This has reduced the number and types of institutions competing for mortgages. Although this may be adding tens of basis points to mortgage rates rather than full percentage points, even a modest increase compounds over the life of a mortgage.
The ripple effects from the artificial intelligence (AI) boom are making housing less affordable. With the economy near full employment, capital is limited. This can cause surges in investment to “crowd out” other areas of the economy by pushing rates higher, suppressing other investment.
Crowding out is usually discussed in relation to government borrowing, but a private investment surge can produce a similar effect—and that’s exactly what’s happening. As the below chart shows, artificial intelligence spending has remained relatively resistant to higher rates, while more rate-sensitive parts of the economy, including housing, have felt the pressure.
Data-center construction may also compete with homebuilding for labor, electrical equipment, grid access, land and financing. While not every dollar invested in AI directly replaces a dollar of residential construction, the economy is being asked to rapidly build the infrastructure for a new technological era while it is already short of homes. This is adding to the costs for first-time home buyers.
Given the salience of the issue in the mind of American voters, politicians have been eager to propose solutions. However, no single measure can solve a problem with several distinct causes. Some proposals target construction costs or housing supply, while others focus on the demand side through lowering mortgage rates. Some have already been put into action. Here, we briefly summarize four efforts to aimed at increasing supply, and two intended to increase demand.
Direct intervention in the mortgage market is an easy way to reduce lending costs. Earlier this year, the administration directed government-sponsored enterprises (GSEs) Fannie Mae and Freddie Mac to purchase $200 billion of agency mortgage-backed securities (MBS). The goal is to increase demand for MBS, reducing rates by narrowing the spread over Treasury yields. Still, the size of the mortgage market makes this intervention a drop in the bucket. Macro drivers have taken the reins since the start of the Iran conflict. Additionally, the GSEs only have so much cash on hand from their retained earnings, limiting their ability to intervene further.12
Bringing additional bank competition back into the mortgage market could be a potentially more important step. Michelle Bowman, a Federal Reserve Board governor, has proposed regulatory changes that could make it less costly for banks to offer and service mortgages.13 She also supports tying bank capital requirements more closely to a borrower’s down payment and the actual risk of the loan. If successful, these measures could reduce some of the hurdles that have led banks to leave the mortgage market, increasing competition and driving down rates.
Policy can help, but U.S. households have always responded to differences in affordability on their own. Geographic mobility has historically been one of the American economy’s great strengths. People moved toward jobs, cheaper land and expanding communities without the friction of having to change nationalities. That process can allow regional differences in housing costs to begin to correct through migration.
We can already see the incentive structure in action through domestic migration data. Visible in the chart below, states with less affordable housing tend to have larger net outflows, while affordable states are seeing net inflows.
The meaning of the American dream may also begin to shift. Homeownership still offers stability and a path to wealth accumulation, but it is not the right financial decision for every household at every point in life. When mortgage rates, transaction costs and price-to-rent ratios are high, renting can preserve geographic flexibility and free capital for other investments. After all, Americans who put their savings in the stock market have on average far outperformed those who invested in real estate over the past few decades.
The housing challenge is ultimately another example of Americans counting on an economic opportunity only to find it out of reach in reality. Affordability is not simply worse than people hoped; it is worse than history suggests it should be, making milestones such as homeownership feel increasingly out of reach. In the midterms, voters demanded visible progress, but there are no quick fixes. Real solutions will take sustained efforts to expand supply, improve the mortgage market and give households more flexibility in how and where they build wealth.
For more information about the housing and mortgage markets, contact your J.P. Morgan team.

We can help you navigate a complex financial landscape. Reach out today to learn how.
Contact usLEARN MORE About Our Firm and Investment Professionals Through FINRA BrokerCheck
To learn more about J.P. Morgan’s investment business, including our accounts, products and services, as well as our relationship with you, please review our J.P. Morgan Securities LLC Form CRS and Guide to Investment Services and Brokerage Products.
JPMorgan Chase Bank, N.A. and its affiliates (collectively "JPMCB") offer investment products, which may include bank-managed accounts and custody, as part of its trust and fiduciary services. Other investment products and services, such as brokerage and advisory accounts, are offered through J.P. Morgan Securities LLC ("JPMS"), a member of FINRA and SIPC. Insurance products are made available through Chase Insurance Agency, Inc. (CIA), a licensed insurance agency, doing business as Chase Insurance Agency Services, Inc. in Florida. JPMCB, JPMS and CIA are affiliated companies under the common control of JPMorgan Chase & Co. Products not available in all states.
Please read the Legal Disclaimer for J.P. Morgan Private Bank regional affiliates and other important information in conjunction with these pages.
Bank deposit products, such as checking, savings and bank lending and related services are offered by JPMorgan Chase Bank, N.A. Member FDIC.
Not a commitment to lend. All extensions of credit are subject to credit approval.