Maximize your legacy: Consider making strategic gifts today to lower future estate taxes
Making a large financial gift can be rewarding—and daunting. Both for you and the recipient(s).
There are many compelling reasons to make large financial gifts during your lifetime if you have both the capacity and the desire to give. For example, gifting from your balance sheet can help you move an asset, along with all of its future appreciation (and potential tax obligations) out of your estate with a single stroke. On an emotional level, you may find it’s deeply satisfying to see how a family member takes advantage of the funds you provide.
However, perhaps you worry about running out of money later in life. Or that your gift will add undue complexity to a child’s or grandchild’s life. Or maybe creating a bequest forces you to confront your own mortality—and you’d rather not.
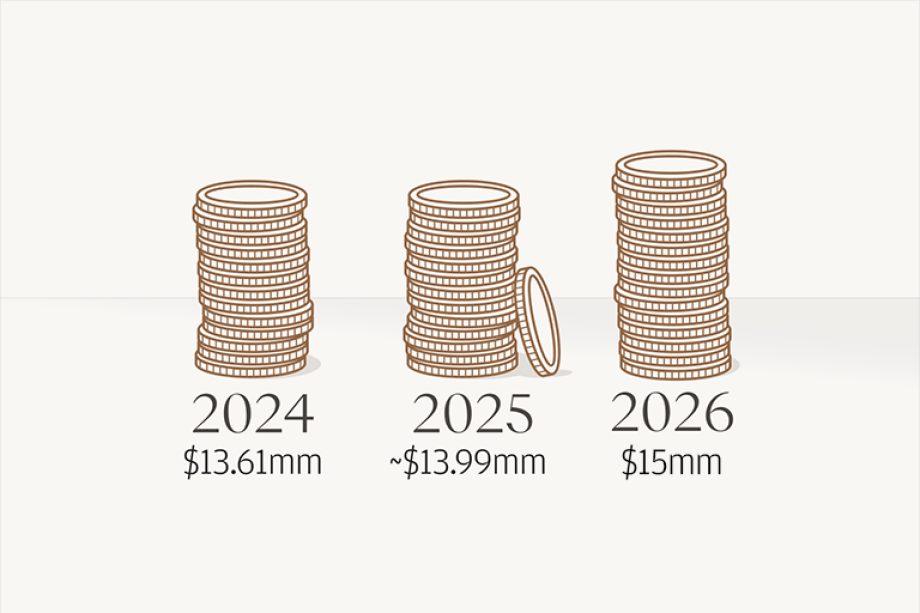
There’s also this to consider: The record-high estate tax exclusion is now permanent at $15MM per person, inflation adjusted, with the passing of the One Big Beautiful Bill in 2025. Married couples can gift $30 million. (This is in addition to the annual tax exemption on gifts of up to $19,000 you can make each year, per recipient, to as many people as you like.)
Answering the following three questions can help you navigate this challenging situation so that you can decide what’s best for you and your heirs.
What do I intend my gift(s) to achieve?
Do you want to cover education costs for your children and/or grandchildren? Create a trust that will provide a safety net for generations to come? Protect and grow a family business?
Clarifying your intentions is an important first step. Putting your plans into action will require more complex decision making, both quantitative and qualitative. For example:
- How much can you gift without compromising your lifestyle or personal financial goals?
- What would be the most tax-efficient way to share your wealth: an outright gift, a trust or another structure?
- Could distributions (say, from a trust) stifle a family member’s growth and development?
- To what degree do you want to involve family members in your decision-making process?
Successful wealth preservation over time often depends on how well a gifting strategy and structure align with a family’s world view and values (i.e., its culture).
Can I afford to gift?
To determine your gift-giving capacity, first calculate how much of your balance sheet should be set aside to cover your:
- Lifestyle spending, such as travel, major purchases, home maintenance and other outlays you will make during your lifetime
- High-priority goals, including education funding for children or grandchildren, charitable giving that you consider to be part of your ongoing lifestyle, etc.
Whatever amount remains on your balance sheet after accounting for these outlays represents your surplus or perpetual growth capital (i.e., your gifting capacity).
Armed with this information, you can move forward with confidence, knowing your core goals are safely secured.
One of the biggest missteps we see clients make is to assume they can—or should—be gifting because they have a taxable estate.
But making an irrevocable gift based solely on a summary figure does not necessarily reflect an individual’s true gifting capacity.
As noted above, before taking steps to share your wealth, it’s critical to make sure you will have the funds you need during your lifetime to meet your core goals and maintain your lifestyle.
Here’s what two clients discovered about their own gifting capacities.
A tale of two families
The Johnson Family and Lee Family had similar intentions: Each wanted to create secure financial futures for their children and grandchildren.
Working with their J.P. Morgan teams and the firm’s Wealth Plan Plus proprietary financial modeling tool, both families were surprised to learn their true gifting capacities.
As the chart illustrates, financial goals—not portfolio size—determined how much each family could comfortably gift to the next generation.
How to calculate gifting capacity

As shown above, although the Lee Family has a portfolio three times larger than that of the Johnson Family, they have a far smaller gifting capacity, given their annual spend rate and planned lake home purchase.
Should I make a gift?
Before you set your wealth transfer plans in motion, consider how your gift(s) are likely to be received. For example, if family members don’t know they will be receiving large amounts of wealth, they may not have the information or tools to successfully steward the money or a family business across multiple generations.
Establishing a group of decision makers and working together to create a family culture that can support your desired intent are as important as your financial calculations. Working with professionals to communicate the right amount of information at the right time can help you or your family achieve desired outcomes.
We can help
Aligning your intentions with your wealth strategies and long-term goals is an evolving process. Your J.P. Morgan team can help you explore your options and determine your gifting capacity, using our Wealth Plan Plus proprietary financial modeling tool.
In this article, we address if you can afford to gift, and the considerations around that decision. This is the first of a three-part article series. In articles II and III, we will be discussing:
II. Great, you’re making a gift! Now what?
III. When making a gift, which policies should you now be considering?
Experience the full possibility of your wealth
We can help you navigate a complex financial landscape. Reach out today to learn how.
Contact us