Policy & Law

U.K. Autumn Budget: New hands, same constraints

Key takeaways

  • The Budget prioritised market confidence over a fiscal reset, preserving fiscal rules and headline Income Tax, National Insurance and VAT rates. With headroom reduced to £15 billion, new spending remained modest and time-limited, while targeted taxes -principally a temporary increase in the bank surcharge - funded lasting measures.
  • The Budget met market expectations for fiscal restraint, keeping the UK out of the spotlight on European fiscal concerns. The reaction was muted: gilts slightly outperformed peers across maturities, while sterling gained marginal support against the US dollar.
  • The Budget offers little near-term support for growth. An external energy shock, persistent inflation and the prospect of higher interest rates keep stagflationary risks in view, while longer-term challenges around debt, productivity and spending remain unresolved.
  • Support for entrepreneurs is targeted rather than broad-based: a proposed Founders’ Relief would offer a 10% Capital Gains Tax (CGT) rate on the first £10 million of qualifying gains, and tax favoured employee share options would expand. Alongside this, the BADR lifetime limit falls to £500,000 from 6 April 2027; Founders’ Relief remains subject to consultation, legislation and stringent eligibility conditions.
  • Investors and savers face higher taxes despite unchanged headline rates on working and dividend income. From 6 April 2027, basic and higher rates on savings and property income rise by a further two percentage points in addition to the increase already announced in 2025, with the top rate reaching 49%; the annual cash ISA subscription limit remains £20,000.

The first Budget of Andy Burnham's premiership, and the first delivered by Chancellor John Healey, opted for continuity over reinvention: fiscal rules intact, headroom under scrutiny and markets watching closely. It was the new government's first real opportunity to set out its economic agenda. In the lead-up to the event, Burnham's public engagements had signalled an intent to ease cost-of-living pressures and pursue devolution (with the state positioned as a catalyst for private investment), while also repeatedly emphasising fiscal restraint.

On balance, the Budget was emblematic of an inherited set of constraints. An energy shock linked to the Middle East has pushed costs higher, the Bank of England has moved from debating cuts to weighing hikes, and gilt yields have climbed to levels last seen decades ago. Much of the fiscal buffer present at the start of the year has been eroded. That seems to have driven the decision to deliver a package that could reassure both markets and voters, keeping any new spending modest and time-limited, while leaning on tax rather than borrowing to fund lasting measures. More ambitious and costly parts of Burnham's agenda seem to have been held back.

A focus on continuity

The pressure in bond markets has been notable. Long-dated yields had climbed through the summer and autumn, alongside a global repricing of government debt. The 30-year gilt yield breached 6% earlier in October — its highest since 1998 — and the 10-year closed at around 5.30% on the eve of the Budget. That left elevated yields and questions about debt sustainability hanging over the event, with a push for a more disciplined fiscal package.

Against this backdrop, the Budget upheld fiscal rules. It is still intended to balance by 2029–30, debt is forecast to fall as a share of the economy, and the push for one fiscal event a year is intact. Manifesto pledges remain unchanged as the Chancellor reaffirmed the government’s commitment to not raise headline rates of Income Tax, National Insurance, or VAT — leaving a narrow set of ways to raise additional money. Healey had already ruled out a higher Capital Gains Tax, warning it could cost rather than raise revenue if the wealthy deferred disposals or left the country. Talk of a lower high-value council tax threshold didn't come to fruition, and elsewhere, the tax package was small and targeted, with the bulk of immediate revenue coming from a temporary higher corporation tax on bank profits.

Higher borrowing costs took a sizeable bite out of the fiscal buffer — eroding around £11 billion of headroom — while stronger tax receipts clawed some of that back. On net, that left the final fiscal headroom at £15 billion, well short of the roughly £30 billion contingency typical before the pandemic. Borrowing was revised slightly higher all the same, but the deficit is expected to decrease to 3.4% of GDP in the next fiscal year.

Hard choices were deferred to next year, with some larger spending decisions left unaddressed. And even on this path, the OBR sees the tax burden climbing to around 39% of GDP by 2031–32, an all-time high and more than seven percentage points above pre-pandemic levels.

A delicate economic balance

The U.K. economy has held up better than expected despite high energy prices and higher rates. But we don't see a meaningful near-term growth boost from the Budget, given the limited scope for fiscal stimulus.

The OBR trimmed its growth path, cutting 2027 to 1.0% from 1.6%, with later years little changed. Before the conflict, inflation had been on course to settle near the Bank of England's 2% target, yet headline CPI rose to a 3.5% annual pace in September from 3.1% in August, its highest since October 2025, and core inflation was an elevated 2.8%. The OBR forecasts CPI at 3.1% in 2026 and 3.4% in 2027, back to target in 2030. Meanwhile, the labour market looks firm: unemployment fell to 4.7% in the three months to August from 4.9% earlier in the summer, with employment rising. The OBR sees it peaking at 5.1% before settling a percentage point lower in the longer run, leaving little slack to pull prices back down on its own.

That affects the Bank of England's policy path. A year ago, the debate was how fast the Bank could cut; in February, the MPC came within one vote of easing to 3.5%. Since then, the Bank Rate has been held at 3.75% at every meeting, dissents have turned more hawkish, and markets now price over 100bps of hikes by the end of next year.

Altogether, the Chancellor faces limited fiscal space. An external energy shock and sticky services inflation keep stagflation risks in view. Longer term, structural challenges remain unresolved, with hard choices still ahead.

Key tax announcements

The measures outlined below combine targeted support for high-growth businesses and employee share ownership with reduced relief for other qualifying business disposals and higher taxes on savings and property income. Alongside these changes, plans for fiscal devolution would give regional authorities a greater role in raising and allocating revenue.

Entrepreneurs

A core aim of the Autumn Budget 2026, Breathing Space for Today, Fresh Hope for the Future, is to strengthen the U.K.’s appeal as a location for entrepreneurs in fast-growth sectors to start and scale their businesses. To support this aim, the government is introducing targeted tax reliefs and broadening the scope for business owners to reward and incentivise key employees. The main measures are outlined below.

Founders’ Relief: From 6 April 2027, the government intends to introduce Founders’ Relief, offering a 10% CGT rate on the first £10 million of qualifying gains for founders of high-growth, innovative companies. Eligibility will be subject to stringent conditions relating to turnover, headcount and/or research and development spending targets, as well as links to the U.K. The relief will be introduced into law through Finance Bill 2026–27, following a technical consultation that concludes on 30 November 2026.

Business Assets Disposal Relief: Alongside the introduction of Founders’ Relief, the government will reduce the lifetime limit on gains eligible for Business Assets Disposal Relief (BADR) from £1 million to £500,000. BADR offers an 18% CGT rate on qualifying disposals. The reduced lifetime limit will apply to disposals made from 6 April 2027.

Enterprise Management Incentives (EMI) 2: From 6 April 2027, the government will increase the Company Share Option Plan (CSOP) individual option limit from £60,000 to £120,000 and remove its interaction with the EMI option limit. Eligible employees will therefore be able to receive the full number of options available under each scheme. The CSOP exercise period will also be extended from 10 to 15 years. To clarify how the schemes fit together, CSOP will be renamed EMI 2, reflecting its role for growing companies that have moved beyond EMI or are not eligible for it.

Investors

While a commitment to not raise income tax on working people was contained within the Labour Manifesto, the government today announced an increase in taxation on investment income.

Higher taxes on investment income: From 6 April 2027, the basic and higher rates of tax on savings and property income will increase by a further 2 percentage points, in addition to the 2 percentage point increase previously announced, meaning that  the top rate on these income sources will reach 49%.

Cash ISAs: The annual subscription limit for cash Individual Savings Accounts (ISAs) will now remain at £20,000 and not be cut to £12,000 as had previously been announced.

The Fiscal Devolution Roadmap

Beyond announced measures for entrepreneurs and investors, the government is publishing the Fiscal Devolution Roadmap, setting out plans to reform regional government funding. Mayors will join the Business Rates Retention system from 2027–28 and receive a share of income tax from 2028–29. Strategic authorities will also be able to introduce visitor levies, with local leaders able to set out plans for investing the revenues by March 2028.

What it means for you

Faced with a shrunken buffer and a nervous bond market, the Chancellor upheld fiscal rules, left headline tax rates unchanged and raised spending from narrower, more targeted bases. But preserving market confidence is not the same as resolving the U.K.'s longer-term fiscal challenges. Debt stands at £3 trillion, interest costs are rising faster than forecast, and the economy's ability to grow its way out of the squeeze still rests on sluggish productivity. The heavy reliance on gilt issuance leaves the public finances highly sensitive to global bond-market sentiment.

Markets had given the government the benefit of the doubt and not baked in a negative risk premium ahead of the announcement date. The budget lived up to these expectations and ensured the U.K. steered clear of the market’s focus on fiscal issues in Europe. Therefore, the reaction was only benign: Gilts slightly outperformed peers across tenors and sterling was supported marginally against the greenback.

Beyond the fiscal outlook, the measures have different implications for business owners and investors: targeted support for qualifying founders and employee share schemes sits alongside reduced relief for other business disposals and higher taxes on savings and property income. It should be noted that most provisions are being brought in in the next tax year and some remain subject to consultation and legislation, such as the new Founders Relief.

Budget at a glance

  • Bank Corporation Tax Surcharge: Temporarily increased from 3% to 6% for 15 months, from 1 January 2027 to 31 March 2028.
  • Capital Gains — Offshore companies attributed to U.K. residents/protected cell companies: Finance Bill 26-27 will amend capital gains participator rules for non-resident close companies to ensure they apply to protected cell companies with effect from 28 October 2026.
  • Capital Gains — Trust exit charge and trustee migration: Administrative easement to the CGT “exit charge” when a trust stops being U.K. resident, to make relocation to the U.K. easier for globally mobile talent. Legislation in Finance Bill 2026–27 applies to exit charges on or after 28 October 2026.
  • High Potential Individual visa expansion: Expanded to include the top 150 global universities.
  • Investors in U.S. Limited Liability Companies (LLCs) and other reverse hybrids: In response to a consultation published in June, the government will create a mechanism to provide double taxation relief for income received by investors from certain foreign entities where relief is currently unavailable. The government has published a response which sets out more details on the mechanism and further steps for consultation ahead of legislation being included in Finance Bill 2027–28.
  • More timely payment for Self-Assessment: From April 2029, Self-Assessment taxpayers who currently make “payments on account” will be required to make more regular in-year payments toward their final bill.
  • Tax treatment of image rights payments: Image rights payments connected to employment will be clarified as taxable employment income with the effective date moved to 6 April 2028.
  • Income Tax — Pension Tax Allowance (PTA): New allowance to stop pensioners with total income up to the full new State Pension from having to pay small amounts of tax. PTA is calculated as 20% of the gap between the full new State Pension and the Personal Allowance; applies automatically for those over State Pension age with income at/below the full new State Pension value; tapered withdrawal for incomes just above. Applies 6 April 2027 to 5 April 2030 and will be uprated in line with the full new State Pension during this Parliament.
  • Business rates — Small Business Rate Relief (SBRR) thresholds for Retail, Hospitality and Leisure (England): From 1 April 2027, thresholds rise. 100% relief up to £18,000 rateable value; tapered relief up to £21,000.
  • Alcohol duty: Duty rates increase in line with RPI to maintain real-terms value. Small Producer Relief becomes relatively more generous via a more generous discount taper for products under 3.5% ABV and an uplift to the marginal discount for 3.5%–8.4% ABV of RPI + 10%. Implemented from 1 February 2027.
  • Annual Tax on Enveloped Dwellings (ATED): Annual charges increase by 3.5% (in line with September 2026 CPI) for the 2027/28 charging period.
  • Tax treatment of stablecoins: Finance Bill 2026/27 will treat eligible stablecoins more like money for tax purposes, changing rules for individuals, trustees and companies while extending withholding tax. Effective from April 2027.

Sources

Budget 2026 Breathing space for today fresh hope for the future

FAQs

FAQs

KEY RISKS

For illustrative purposes only. Opinions, estimates, forecasts, comparisons and statements of financial market trends constitute our judgment and are subject to change without notice. The views and strategies described may not be suitable for all investors. We do not provide tax advice.

Important Information

This material is for information purposes only, and may inform you of certain products and services offered by private banking businesses, part of JPMorgan Chase & Co. (“JPM”). Products and services described, as well as associated fees, charges and interest rates, are subject to change in accordance with the applicable account agreements and may differ among geographic locations. Not all products and services are offered at all locations. If you are a person with a disability and need additional support accessing this material, please contact your J.P. Morgan team or email us at accessibility.support@jpmorgan.com for assistance. Please read all Important Information.

GENERAL RISKS & CONSIDERATIONS

Any views, strategies or products discussed in this material may not be appropriate for all individuals and are subject to risks. Investors may get back less than they invested, and past performance is not a reliable indicator of future results. Asset allocation/diversification does not guarantee a profit or protect against loss. Nothing in this material should be relied upon in isolation for the purpose of making an investment decision. You are urged to consider carefully whether the services, products, asset classes (e.g. equities, fixed income, alternative investments, commodities, etc.) or strategies discussed are suitable to your needs. You must also consider the objectives, risks, charges, and expenses associated with an investment service, product or strategy prior to making an investment decision. For this and more complete information, including discussion of your goals/situation, contact your J.P. Morgan team.

NON-RELIANCE

Certain information contained in this material is believed to be reliable; however, JPM does not represent or warrant its accuracy, reliability or completeness, or accept any liability for any loss or damage (whether direct or indirect) arising out of the use of all or any part of this material. No representation or warranty should be made with regard to any computations, graphs, tables, diagrams or commentary in this material, which are provided for illustration/ reference purposes only. The views, opinions, estimates and strategies expressed in this material constitute our judgment based on current market conditions and are subject to change without notice. JPM assumes no duty to update any information in this material in the event that such information changes. Views, opinions, estimates and strategies expressed herein may differ from those expressed by other areas of JPM, views expressed for other purposes or in other contexts, and this material should not be regarded as a research report. Any projected results and risks are based solely on hypothetical examples cited, and actual results and risks will vary depending on specific circumstances. Forward-looking statements should not be considered as guarantees or predictions of future events.

Nothing in this document shall be construed as giving rise to any duty of care owed to, or advisory relationship with, you or any third party. Nothing in this document shall be regarded as an offer, solicitation, recommendation or advice (whether financial, accounting, legal, tax or other) given by J.P. Morgan and/or its officers or employees, irrespective of whether or not such communication was given at your request. J.P. Morgan and its affiliates and employees do not provide tax, legal or accounting advice. You should consult your own tax, legal and accounting advisors before engaging in any financial transactions.

Your investments and potential conflicts of interest

Conflicts of interest will arise whenever JPMorgan Chase Bank, N.A. or any of its affiliates (together, “J.P. Morgan”) have an actual or perceived economic or other incentive in its management of our clients’ portfolios to act in a way that benefits J.P. Morgan. Conflicts will result, for example (to the extent the following activities are permitted in your account): (1) when J.P. Morgan invests in an investment product, such as a mutual fund, structured product, separately managed account or hedge fund issued or managed by JPMorgan Chase Bank, N.A. or an affiliate, such as J.P. Morgan Investment Management Inc.; (2) when a J.P. Morgan entity obtains services, including trade execution and trade clearing, from an affiliate; (3) when J.P. Morgan receives payment as a result of purchasing an investment product for a client’s account; or (4) when J.P. Morgan receives payment for providing services (including shareholder servicing, recordkeeping or custody) with respect to investment products purchased for a client’s portfolio. Other conflicts will result because of relationships that J.P. Morgan has with other clients or when J.P. Morgan acts for its own account.

Investment strategies are selected from both J.P. Morgan and third-party asset managers and are subject to a review process by our manager research teams. From this pool of strategies, our portfolio construction teams select those strategies we believe fit our asset allocation goals and forward-looking views in order to meet the portfolio's investment objective.

As a general matter, we prefer J.P. Morgan managed strategies. We expect the proportion of J.P. Morgan managed strategies will be high (in fact, up to 100 percent) in strategies such as, for example, cash and high-quality fixed income, subject to applicable law and any account-specific considerations.

While our internally managed strategies generally align well with our forward-looking views, and we are familiar with the investment processes as well as the risk and compliance philosophy of the firm, it is important to note that J.P. Morgan receives more overall fees when internally managed strategies are included. We offer the option of choosing to exclude J.P. Morgan managed strategies (other than cash and liquidity products) in certain portfolios.

The Six Circles Funds are U.S.-registered mutual funds managed by J.P. Morgan and sub-advised by third parties. Although considered internally managed strategies, JPMC does not retain a fee for fund management or other fund services.

Legal entity, brand & regulatory information

In the United States, bank deposit accounts and related services, such as checking, savings and bank lending, are offered by JPMorgan Chase Bank, N.A. Member FDIC.

JPMorgan Chase Bank, N.A. and its affiliates (collectively “JPMCB”) offer investment products, which may include bank managed investment accounts and custody, as part of its trust and fiduciary services. Other investment products and services, such as brokerage and advisory accounts, are offered through J.P. Morgan Securities LLC (“JPMS”), a member of FINRA and SIPC. Insurance products are made available through Chase Insurance Agency, Inc. (CIA), a licensed insurance agency, doing business as Chase Insurance Agency Services, Inc. in Florida. JPMCB, JPMS and CIA are affiliated companies under the common control of JPM. Products not available in all states.

In Germany, this material is issued by J.P. Morgan SE, with its registered office at Taunustor 1 (TaunusTurm), 60310 Frankfurt am Main, Germany, authorized by the Bundesanstalt für Finanzdienstleistungsaufsicht (BaFin) and jointly supervised by the BaFin, the German Central Bank (Deutsche Bundesbank) and the European Central Bank (ECB). In Luxembourg, this material is issued by J.P. Morgan SE – Luxembourg Branch, with registered office at European Bank and Business Centre, 6 route de Treves, L-2633, Senningerberg, Luxembourg, authorized by the Bundesanstalt für Finanzdienstleistungsaufsicht (BaFin) and jointly supervised by the BaFin, the German Central Bank (Deutsche Bundesbank) and the European Central Bank (ECB); J.P. Morgan SE – Luxembourg Branch is also supervised by the Commission de Surveillance du Secteur Financier (CSSF); registered under R.C.S Luxembourg B255938. In the United Kingdom, this material is issued by J.P. Morgan SE – London Branch, registered office at 25 Bank Street, Canary Wharf, London E14 5JP, authorized by the Bundesanstalt für Finanzdienstleistungsaufsicht (BaFin) and jointly supervised by the BaFin, the German Central Bank (Deutsche Bundesbank) and the European Central Bank (ECB); J.P. Morgan SE – London Branch is also supervised by the Financial Conduct Authority and Prudential Regulation Authority. In Spain, this material is distributed by J.P. Morgan SE, Sucursal en España, with registered office at Paseo de la Castellana, 31, 28046 Madrid, Spain, authorized by the Bundesanstalt für Finanzdienstleistungsaufsicht (BaFin) and jointly supervised by the BaFin, the German Central Bank (Deutsche Bundesbank) and the European Central Bank (ECB); J.P. Morgan SE, Sucursal en España is also supervised by the Spanish Securities Market Commission (CNMV); registered with Bank of Spain as a branch of J.P. Morgan SE under code 1567. In Italy, this material is distributed by J.P. Morgan SE – Milan Branch, with its registered office at Via Cordusio, n.3, Milan 20123, Italy, authorized by the Bundesanstalt für Finanzdienstleistungsaufsicht (BaFin) and jointly supervised by the BaFin, the German Central Bank (Deutsche Bundesbank) and the European Central Bank (ECB); J.P. Morgan SE – Milan Branch is also supervised by Bank of Italy and the Commissione Nazionale per le Società e la Borsa (CONSOB); registered with Bank of Italy as a branch of J.P. Morgan SE under code 8076; Milan Chamber of Commerce Registered Number: REA MI 2536325. In the Netherlands, this material is distributed by J.P. Morgan SE – Amsterdam Branch, with registered office at World Trade Centre, Tower B, Strawinskylaan 1135, 1077 XX, Amsterdam, The Netherlands, authorized by the Bundesanstalt für Finanzdienstleistungsaufsicht (BaFin) and jointly supervised by the BaFin, the German Central Bank (Deutsche Bundesbank) and the European Central Bank (ECB); J.P. Morgan SE – Amsterdam Branch is also supervised by De Nederlandsche Bank (DNB) and the Autoriteit Financiële Markten (AFM) in the Netherlands. Registered with the Kamer van Koophandel as a branch of J.P. Morgan SE under registration number 72610220. In Denmark, this material is distributed by J.P. Morgan SE – Copenhagen Branch, filial af J.P. Morgan SE, Tyskland, with registered office at Kalvebod Brygge 39-41, 1560 København V, Denmark, authorized by the Bundesanstalt für Finanzdienstleistungsaufsicht (BaFin) and jointly supervised by the BaFin, the German Central Bank (Deutsche Bundesbank) and the European Central Bank (ECB); J.P. Morgan SE – Copenhagen Branch, filial af J.P. Morgan SE, Tyskland is also supervised by Finanstilsynet (Danish FSA) and is registered with Finanstilsynet as a branch of J.P. Morgan SE under code 29010. In Sweden, this material is distributed by J.P. Morgan SE – Stockholm Bankfilial, with registered office at Hamngatan 15, Stockholm, 11147, Sweden, authorized by the Bundesanstalt für Finanzdienstleistungsaufsicht (BaFin) and jointly supervised by the BaFin, the German Central Bank (Deutsche Bundesbank) and the European Central Bank (ECB); J.P. Morgan SE – Stockholm Bankfilial is also supervised by Finansinspektionen (Swedish FSA); registered with Finansinspektionen as a branch of J.P. Morgan SE. In Belgium, this material is distributed by J.P. Morgan SE – Brussels Branch with registered office at 35 Boulevard du Régent, 1000, Brussels, Belgium, authorized by the Bundesanstalt für Finanzdienstleistungsaufsicht (BaFin) and jointly supervised by the BaFin, the German Central Bank (Deutsche Bundesbank) and the European Central Bank (ECB); J.P. Morgan SE Brussels Branch is also supervised by the National Bank of Belgium (NBB) and the Financial Services and Markets Authority (FSMA) in Belgium; registered with the NBB under registration number 0715.622.844. In Greece, this material is distributed by J.P. Morgan SE – Athens Branch, with its registered office at 3 Haritos Street, Athens, 10675, Greece, authorized by the Bundesanstalt für Finanzdienstleistungsaufsicht (BaFin) and jointly supervised by the BaFin, the German Central Bank (Deutsche Bundesbank) and the European Central Bank (ECB); J.P. Morgan SE – Athens Branch is also supervised by Bank of Greece; registered with Bank of Greece as a branch of J.P. Morgan SE under code 124; Athens Chamber of Commerce Registered Number 158683760001; VAT Number 99676577. In France, this material is distributed by J.P. Morgan SE – Paris Branch, with its registered office at 14, Place Vendôme 75001 Paris, France, authorized by the Bundesanstaltfür Finanzdienstleistungsaufsicht(BaFin) and jointly supervised by the BaFin, the German Central Bank (Deutsche Bundesbank) and the European Central Bank (ECB) under code 842 422 972; J.P. Morgan SE – Paris Branch is also supervised by the French banking authorities the Autorité de Contrôle Prudentiel et de Résolution (ACPR) and the Autorité des Marchés Financiers (AMF). In Switzerland, this material is distributed by J.P. Morgan (Suisse) SA, with registered address at rue du Rhône, 35, 1204, Geneva, Switzerland, which is authorised and supervised by the Swiss Financial Market Supervisory Authority (FINMA) as a bank and a securities dealer in Switzerland.

In Hong Kong, this material is distributed by JPMCB, Hong Kong branch. JPMCB, Hong Kong branch is regulated by the Hong Kong Monetary Authority and the Securities and Futures Commission of Hong Kong. In Hong Kong, we will cease to use your personal data for our marketing purposes without charge if you so request. In Singapore, this material is distributed by JPMCB, Singapore branch. JPMCB, Singapore branch is regulated by the Monetary Authority of Singapore. Dealing and advisory services and discretionary investment management services are provided to you by JPMCB, Hong Kong/Singapore branch (as notified to you). Banking and custody services are provided to you by JPMCB Hong Kong/ Singapore Branch (as notified to you). For materials which constitute product advertisement under the Securities and Futures Act and the Financial Advisers Act, this advertisement has not been reviewed by the Monetary Authority of Singapore. JPMorgan Chase Bank, N.A., a national banking association chartered under the laws of the United States, and as a body corporate, its shareholder’s liability is limited. It is registered as a foreign company in Australia with the Australian Registered Body Number 074 112 011.

With respect to countries in Latin America, the distribution of this material may be restricted in certain jurisdictions. We may offer and/or sell to you securities or other financial instruments which may not be registered under, and are not the subject of a public offering under, the securities or other financial regulatory laws of your home country. Such securities or instruments are offered and/or sold to you on a private basis only. Any communication by us to you regarding such securities or instruments, including without limitation the delivery of a prospectus, term sheet or other offering document, is not intended by us as an offer to sell or a solicitation of an offer to buy any securities or instruments in any jurisdiction in which such an offer or a solicitation is unlawful. Furthermore, such securities or instruments may be subject to certain regulatory and/or contractual restrictions on subsequent transfer by you, and you are solely responsible for ascertaining and complying with such restrictions. To the extent this content makes reference to a fund, the Fund may not be publicly offered in any Latin American country, without previous registration of such fund´s securities in compliance with the laws of the corresponding jurisdiction.

JPMorgan Chase Bank, N.A., a national banking association chartered under the laws of the United States, and as a body corporate, its shareholder’s liability is limited. It is registered as a foreign company in Australia with the Australian Registered Body Number 074 112 011. JPMS is a registered foreign company (overseas) (ARBN 109293610) incorporated in Delaware, U.S.A. Under Australian financial services licensing requirements, carrying on a financial services business in Australia requires a financial service provider, such as J.P. Morgan Securities LLC (JPMS), to hold an Australian Financial Services Licence (AFSL), unless an exemption applies. JPMS is exempt from the requirement to hold an AFSL under the Corporations Act 2001 (Cth) (Act) in respect of financial services it provides to you, and is regulated by the SEC, FINRA and CFTC under US laws, and its shareholder’s liability is limited. Material provided by JPMS in Australia is to “wholesale clients” only. The information provided in this material is not intended to be, and must not be, distributed or passed on, directly or indirectly, to any other class of persons in Australia. For the purposes of this paragraph the term “wholesale client” has the meaning given in section 761G of the Act. Please inform us immediately if you are not a Wholesale Client now or if you cease to be a Wholesale Client at any time in the future.

This material has not been prepared specifically for Australian investors. It:

  • may contain references to dollar amounts which are not Australian dollars;
  • may contain financial information which is not prepared in accordance with Australian law or practices;
  • may not address risks associated with investment in foreign currency denominated investments; and
  • does not address Australian tax issues.

References to “J.P. Morgan” are to JPM, its subsidiaries and affiliates worldwide. “J.P. Morgan Private Bank” is the brand name for the private banking business conducted by JPM. This material is intended for your personal use and should not be circulated to or used by any other person, or duplicated for non-personal use, without our permission. If you have any questions or no longer wish to receive these communications, please contact your J.P. Morgan team.

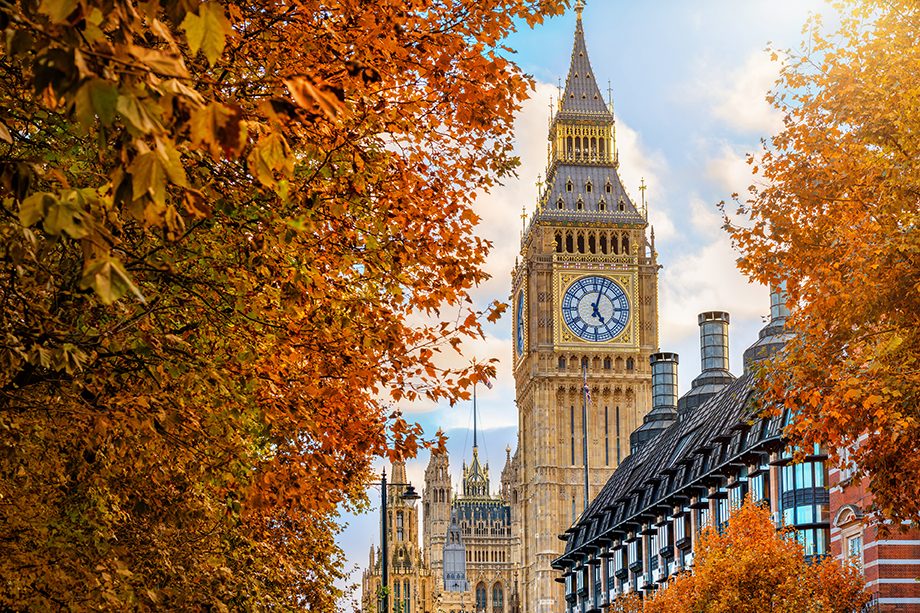
The 2026 Autumn Budget kept headline tax rates unchanged, leaning instead on targeted measures like a temporary bank surcharge hike and reduced business reliefs to raise revenue.

You may also like

Aug 12, 2025
Reforming rates: Capital Gains Tax and Carried Interest

Experience the full possibility of your wealth

We can help you navigate a complex financial landscape. Reach out today to learn how.

Contact us

LEARN MORE About Our Firm and Investment Professionals Through FINRA BrokerCheck


To learn more about J.P. Morgan’s investment business, including our accounts, products and services, as well as our relationship with you, please review our J.P. Morgan Securities LLC Form CRS and Guide to Investment Services and Brokerage Products. 


JPMorgan Chase Bank, N.A. and its affiliates (collectively "JPMCB") offer investment products, which may include bank-managed accounts and custody, as part of its trust and fiduciary services. Other investment products and services, such as brokerage and advisory accounts, are offered through J.P. Morgan Securities LLC ("JPMS"), a member of FINRA and SIPC. Insurance products are made available through Chase Insurance Agency, Inc. (CIA), a licensed insurance agency, doing business as Chase Insurance Agency Services, Inc. in Florida. JPMCB, JPMS and CIA are affiliated companies under the common control of JPMorgan Chase & Co. Products not available in all states.


Please read the Legal Disclaimer for J.P. Morgan Private Bank regional affiliates and other important information in conjunction with these pages.

INVESTMENT AND INSURANCE PRODUCTS ARE: • NOT FDIC INSURED • NOT INSURED BY ANY FEDERAL GOVERNMENT AGENCY • NOT A DEPOSIT OR OTHER OBLIGATION OF, OR GUARANTEED BY, JPMORGAN CHASE BANK, N.A. OR ANY OF ITS AFFILIATES • SUBJECT TO INVESTMENT RISKS, INCLUDING POSSIBLE LOSS OF THE PRINCIPAL AMOUNT INVESTED
Bank deposit products, such as checking, savings and bank lending and related services are offered by JPMorgan Chase Bank, N.A. Member FDIC. Not a commitment to lend. All extensions of credit are subject to credit approval.